Just because a property looks cheap does not mean it offers a strong investment. The right question is whether its likely returns justify its full cost and risk.
If you are deciding how to evaluate property investment in the UAE, start with five checks. Compare the numbers, study the area, and set your plan before committing.
1. Calculate the rental yield
Rental yield compares a property’s rental income with its purchase price or total investment cost. It offers a useful starting point for evaluating rental income.
Gross yield gives a quick comparison, but it excludes ownership expenses. For a more complete estimate, deduct expected recurring costs, such as service charges, maintenance, and management fees. Then compare the remaining rental income with your total investment, including purchase and closing costs.
Use rent estimates for comparable properties and the actual costs associated with the unit. Account for factors such as location, property type, occupancy, and ongoing expenses. These can affect the result, so avoid treating one general yield figure as a reliable benchmark for every property.
2. Assess potential for capital appreciation
Rental income is only one possible return. Capital appreciation means the property’s value rises over time. It can support long-term gains, but it never guarantees a profit.
Check what could make the area more attractive to future residents and buyers. Consider transport links, schools, shops, healthcare, and planned infrastructure. These local and economic factors can influence future value.
However, do not rely on a development announcement alone. Compare current prices and nearby alternatives. Ask whether future growth already appears in the asking price.
3. Test real tenant and buyer demand
A property needs a likely renter or future buyer. Otherwise, attractive projections may not translate into occupancy or resale interest.
Review comparable rental listings and property types in the same community. Look for practical features that serve the people you expect to attract, such as access to transport, workplaces, and daily amenities. A property’s location and convenience can influence tenant interest and occupancy.
Compare search-interest trends by location and property type. Treat that interest as one signal, not proof of signed leases or completed sales.
4. Check upcoming supply
A busy construction pipeline can change the outlook. If many similar homes reach the market, landlords may face stronger competition. Higher supply can also increase vacancies or slow rent growth.
Before buying, review new projects and planned handovers around the property. Compare those units with yours by price, size, facilities, and location. Supply and demand conditions can differ by community and segment, so assess the exact local market.
Then ask a simple question: if tenants gain more choices, what would make them choose this property?
5. Decide your exit strategy in advance
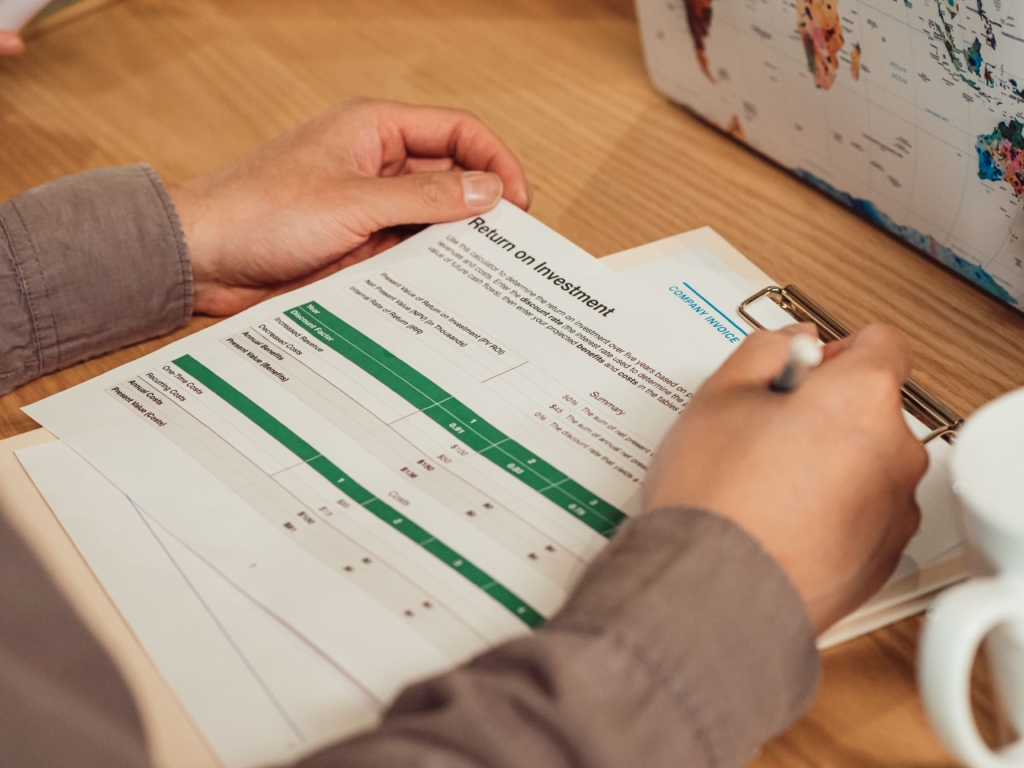
Choose your main goal before you buy. Are you targeting regular rent, long-term appreciation, or resale after a planned holding period?
Your answer affects the property, location, budget, and timeline. A clear exit plan weighs resale demand, transaction costs, and likely selling time. Before making an offer, write down:
- Your intended holding period.
- The return you need after estimated costs.
- The conditions that would prompt you to sell or hold.
- A backup plan if rent, occupancy, or resale demand falls short.
Bring the five checks together
A strong investment is more than an appealing property or a low asking price. It is an asset whose income, growth prospects, demand, supply outlook, and exit plan fit your goals. Therefore, compare the full costs with realistic rental estimates. Check the area’s demand and competing supply. Finally, decide how and when you might exit.
Before you buy, ask: Do the numbers still make sense after costs, and would you feel comfortable holding this property if the market changed?
